TMCnet News
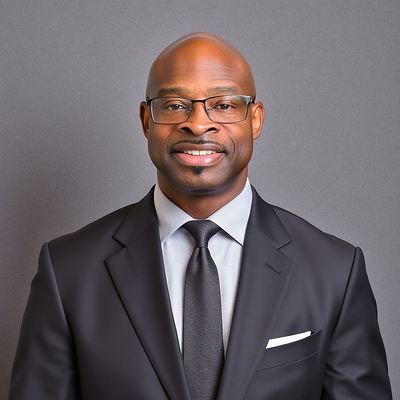
Why Bank Remediation Falls Short When Institutions Treat Findings in IsolationAs the OCC continues to issue and terminate bank enforcement actions, FFERM founder and CEO Dr. Jeffrey L. Edwards says institutions must look beyond closing individual findings and identify the interconnected risk failures that allowed them to develop. CHARLOTTE, N.C., Aug. 3, 2026 /PRNewswire/ -- A consent order can require a bank to correct identified deficiencies. Compliance with the order, however, does not necessarily mean the institution understands the governance, control, or risk-management weaknesses that allowed the problem to develop. Dr. Jeffrey L. Edwards, founder of FFERM Technologies, a financial risk intelligence company, warns that banks under enforcement pressure can mistake completion of required remediation for correction of the underlying risk system.
"Banks often resolve this issue from a short-term perspective so they can get the enforcement action lifted," Dr. Edwards said. "They address what regulators identified, but not the root of the problem. That means they are treating the symptom, not the cause." Enforcement Identifies the Issue, Not Always the Cause For Dr. Edwards, enforcement identifies what must be corrected. The bank's risk program must also determine why the problem developed, what other areas may be affected, and whether the same weakness is emerging elsewhere. A cited deficiency can be connected to broader weaknesses in governance, data, controls, escalation, or board reporting. Correcting the finding may satisfy an immediae regulatory requirement while leaving the institution without a clear understanding of how exposures interact across the organization or where controls are failing. Operational failures rarely remain isolated. A breakdown involving people, processes, or systems can trigger a chain reaction, creating financial exposure before eventually becoming a regulatory issue. Viewed individually, each risk may appear manageable. Viewed together, they may expose interconnected weaknesses across the organization. "Bank boards should begin with one question: 'Why did it happen?'" Dr. Edwards said. "It sounds simple, but people answer it quickly because they think they know. Without evidence, the answer may be opinion rather than fact." Static Reports Do Not Explain Risk Behavior "Reports give you only what you give them," Dr. Edwards said. "A report is a flat, single-purpose document. It can support a decision, but intelligence provides the information and framework leaders need to make decisions as conditions change." Dr. Edwards argues remediation priorities should be based on evidence linking the finding to relevant processes, controls, owners, data, and downstream effects, not on the volume of documentation produced. Traditional scoring may calculate likelihood and severity without showing which weakness should be addressed first. Dr. Edwards says remediation teams must be able to distinguish the visible consequence from the control failure, creating the broader exposure. Otherwise, the institution may complete remediation tasks without fixing the source of the risk. Community Banks Need Proportionate, Usable Risk Intelligence "Small banks do not always have the resources to buy a major enterprise platform or bring in a large consulting firm," Dr. Edwards said. "But they still need to understand root cause, prioritize remediation, and see how risk is behaving across the institution." From Checklist Remediation to Risk Intelligence During enforcement remediation, the cited finding is rarely the only issue that matters. Banks must determine whether the issue is isolated, whether similar failures exist elsewhere, and which corrective action reaches the source of the problem first. "Compounding and predictability help banks get closer to the root cause by showing how risk spreads and when it may emerge," Dr. Edwards said. "The focus is not only the calculation. It is the behavior of the risk and what the institution can do about it." About FFERM Technologies FFERM Technologies is a financial risk intelligence company founded by Dr. Jeffrey L. Edwards, a 30+ year financial services and risk executive. The company developed a patent-pending Four-Factor Enterprise Risk Management methodology that expands beyond traditional likelihood-and-severity scoring to include Compounding and Predictability. FFERM helps financial institutions identify, quantify and prioritize interconnected, systemic risks that traditional models can miss, transforming risk management from a static compliance function into dynamic, forward-looking intelligence. FFERM's platform is designed for regulated financial institutions, including banks, credit unions, insurers, RIAs and broker/dealers. For more information, visit ffermtech.com. References
Media Inquiries:
SOURCE FFERM Technologies 
|
 View original content to download multimedia: